
Top 3 Recommended Policies
By: Jackson Hering
Licensed Personal Insurance Specialist
425-409-2497
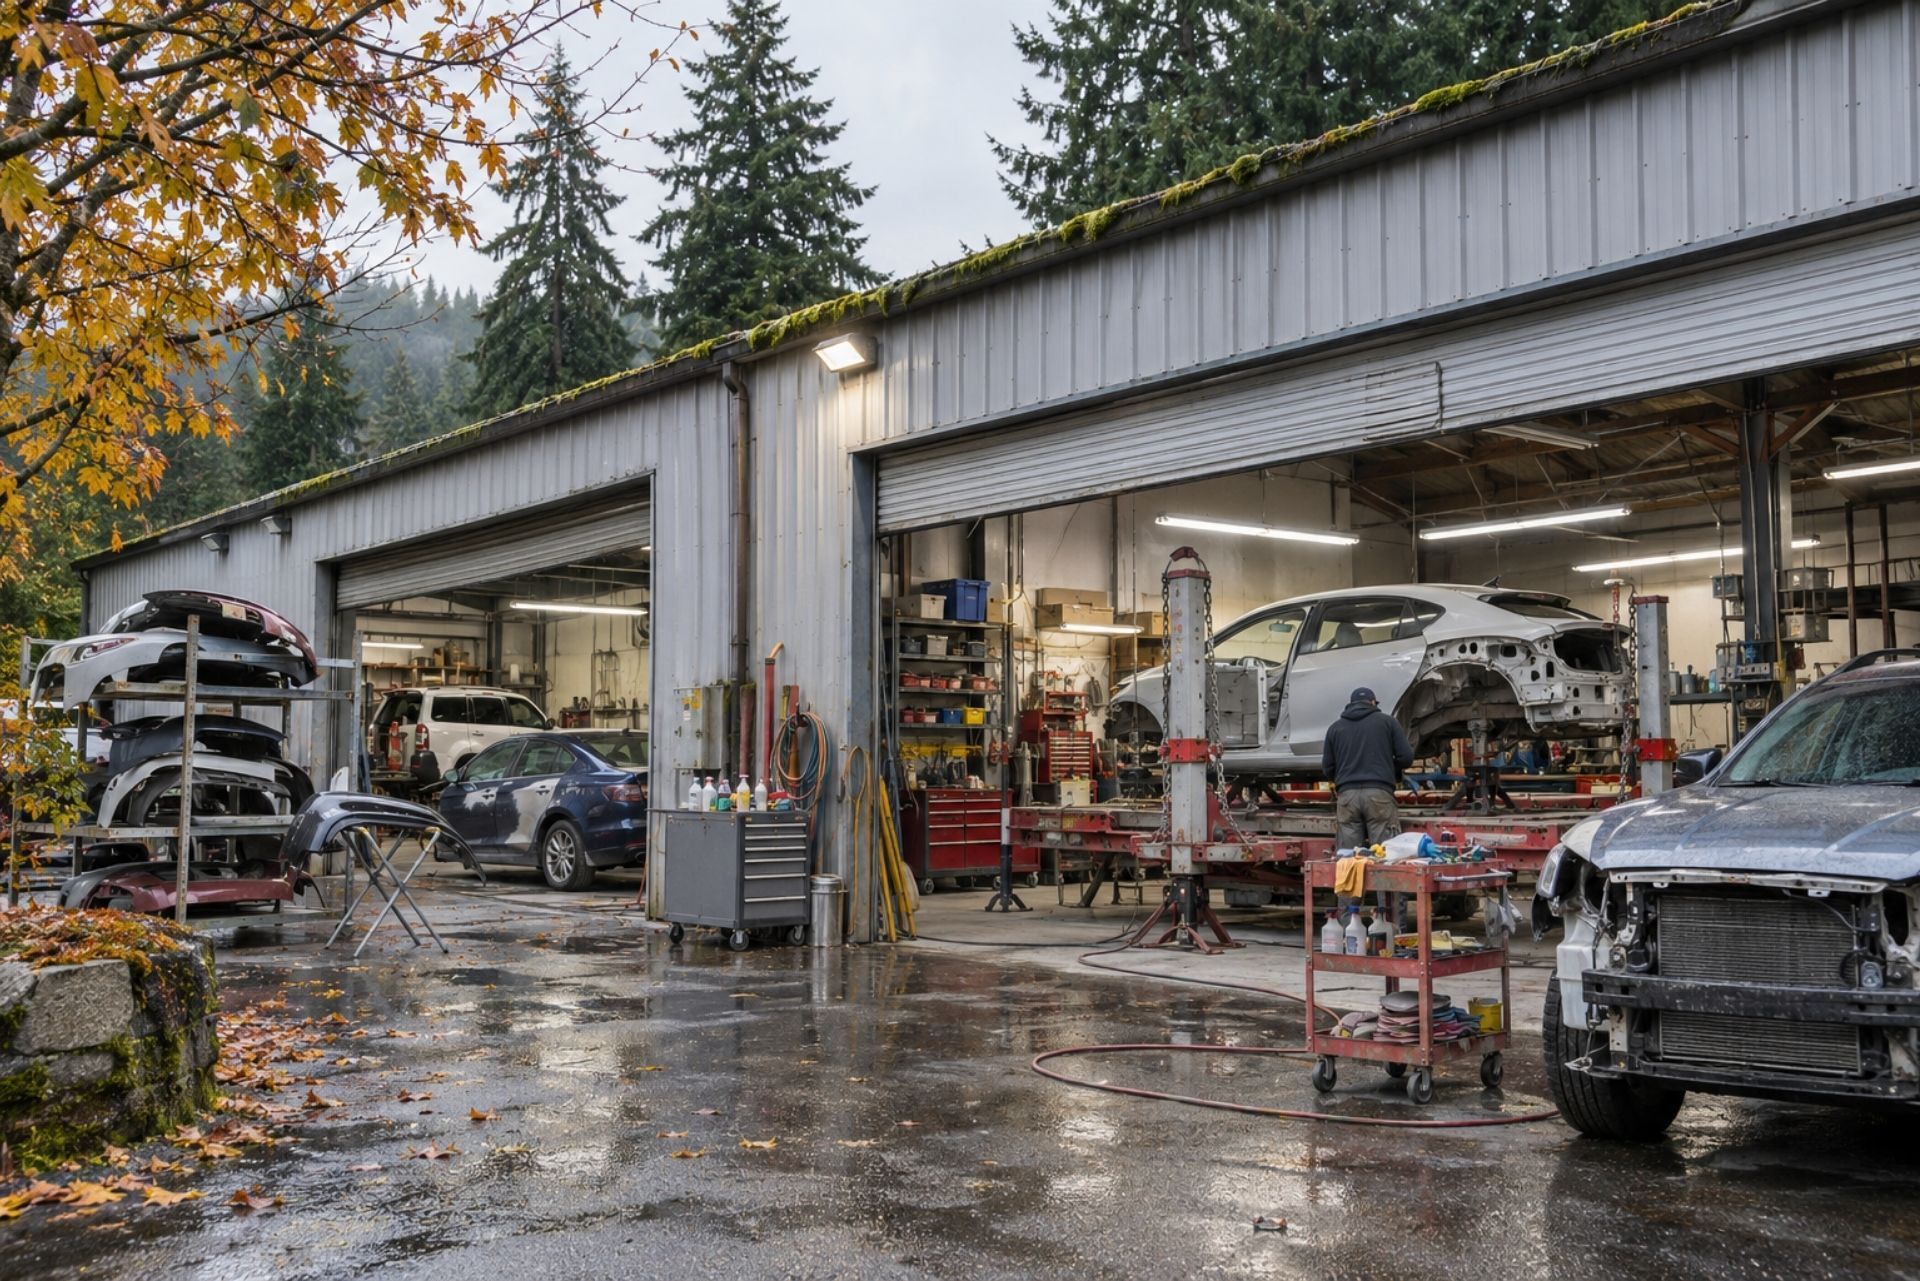
Picture a Friday afternoon in a Tacoma collision shop. A customer's late-model SUV sits in the lot waiting on a bumper cover, a freshly sprayed Tesla is curing in the booth, and a tech is wrestling a frame rack into position. Over one weekend, a catalytic converter thief, a booth fire, or a strained back could each turn into a five-figure claim. Each one lands on a different part of your insurance program.
Most Washington body shop owners we talk to carry some coverage. Fewer have coverage that matches how a collision operation actually loses money. This guide to
auto body shop insurance in Washington explains how garagekeepers, booth and equipment protection,
pollution liability, property, and the state's monopoly workers' comp system fit together. It also shows where the gaps usually hide.
Risk Management for Washington Auto Body Shops
Insurance pays for losses. Risk management decides how many losses you have, and underwriters price your policy on that track record. A shop with clean loss runs, documented procedures, and a tidy booth area gets better terms than a similar shop that treats safety as paperwork.
Repair costs keep climbing. The CPI for motor vehicle body work has shown an average annual inflation rate of 4.18% leading into 2026. The median collision repair now runs about $725, and more than half of tracked repairs exceed $1,000. Every damaged customer vehicle costs more to make right than it did three years ago, and your limits need to keep pace.
Start with the controls underwriters ask about most:
- Key control: Use a locked key box or electronic key management, and log who takes keys and when.
- Vehicle intake photos: Photograph every car at drop-off, including existing dents, wheel rash, and interior condition.
- Lot security: Install lighting, fencing, and cameras that cover the lot and record overnight.
- Booth maintenance logs: Record filter changes, fire suppression inspections, and cleaning dates.
- Written test-drive policy: Limit test drives to authorized, licensed employees with a defined route.
This matters because claim disputes often come down to documentation. When a customer says your crew scratched their quarter panel, an intake photo settles the question in seconds.
Scale matters too. A two-bay independent shop and a 20-employee MSO facility handling DRP work have very different exposures. Larger shops should expect more scrutiny on fleet storage, sublet vendors, and employee driving records.
Protecting Customer Vehicles with Garagekeepers Liability
Your general liability policy almost certainly excludes damage to property in your "care, custody, or control." That exclusion covers every customer car in your bays and on your lot. Garagekeepers coverage fills that gap, and for a body shop it's often the most heavily used policy you'll carry.
Some Washington automotive service operations face a hard floor. State rules require certain service centers to maintain at least $50,000 in garagekeepers liability and $1 million per occurrence in operations coverage. Treat that as a minimum and not a target. A single high-end EV can be worth more than $50,000, and a lot full of vehicles can represent hundreds of thousands in exposure.
To set your limit, look at the highest value you realistically hold on a busy day, not your average. If you're holding a backlog of total-loss vehicles waiting on adjusters, or storage cars over the holidays, count those too.
Legal Liability vs. Direct Primary Coverage
Garagekeepers comes in three main forms, and choosing the wrong one is one of the most common mistakes we see.
| Coverage Form | When It Pays | Best For |
|---|---|---|
| Legal Liability | Only if your shop is legally at fault | Low-theft rural areas, tight budgets |
| Direct Excess | Regardless of fault, after the owner's auto policy pays | Shops wanting goodwill without primary cost |
| Direct Primary | Regardless of fault, before the owner's policy | Urban shops, high-value vehicles |
Under legal liability, if a windstorm drops a tree branch on a customer's car and you weren't negligent, your policy won't pay. The customer files on their own auto policy, pays their deductible, and often blames you anyway. In Seattle and Tacoma, industry specialists generally recommend direct primary for exactly this reason: it pays for the damage whether or not you were at fault.
Common Claims: Vandalism, Theft, and Test Drives
Vehicle thefts in Washington have risen 31% statewide in recent annual data, and shop lots are attractive targets. Overnight vehicles with keys stored on site, high-demand catalytic converters, and expensive wheels draw thieves. Underwriters know this, and premiums reflect it.
The claims we see most often include:
- Break-ins and catalytic converter theft from lot-stored vehicles
- Vandalism, including keyed paint and smashed glass, often on freshly repaired cars
- Fire damage that spreads between parked vehicles
- Test-drive collisions after a repair
One thing to keep in mind: whether a test-drive accident falls under garagekeepers or your garage liability auto coverage depends on policy wording. Ask your agent to show you, in writing, which policy responds.
Insuring Your Paint Booth and Specialized Equipment
A downdraft paint booth, a frame machine, a resistance spot welder, and ADAS calibration equipment can easily represent your biggest capital investment. A standard property policy may cover them, but often only for named perils like fire. That leaves mechanical and electrical failure uncovered.
Equipment breakdown coverage handles the failures property policies exclude. Think of a burned-out booth motor, a fried control board in the cure cycle, or a power surge that kills your spectrophotometer. These failures don't just cost repair money. They stop production, so pair equipment breakdown with business income coverage for the downtime.
Booth fires get special attention from underwriters. Spray finishing operations generally follow NFPA 33, which addresses fire protection, ventilation, and electrical requirements for spray areas. Your local fire marshal and your carrier will both expect you to maintain the booth's suppression system, keep filters changed, and control overspray buildup. A booth fire caused by neglected filters can lead to a denied or reduced claim if your policy includes protective safeguard conditions.
Here's what that means for you: read your property policy for a protective safeguards endorsement. If it requires a working suppression system and yours lapses an inspection, coverage could be voided for fire losses.
Also schedule high-value portable tools and diagnostic scanners under an inland marine or tools floater. These items move around the shop and sometimes leave it. Tool theft from a tech's cart rarely meets a property deductible, but a floater can respond.
Pollution Liability and Environmental Compliance
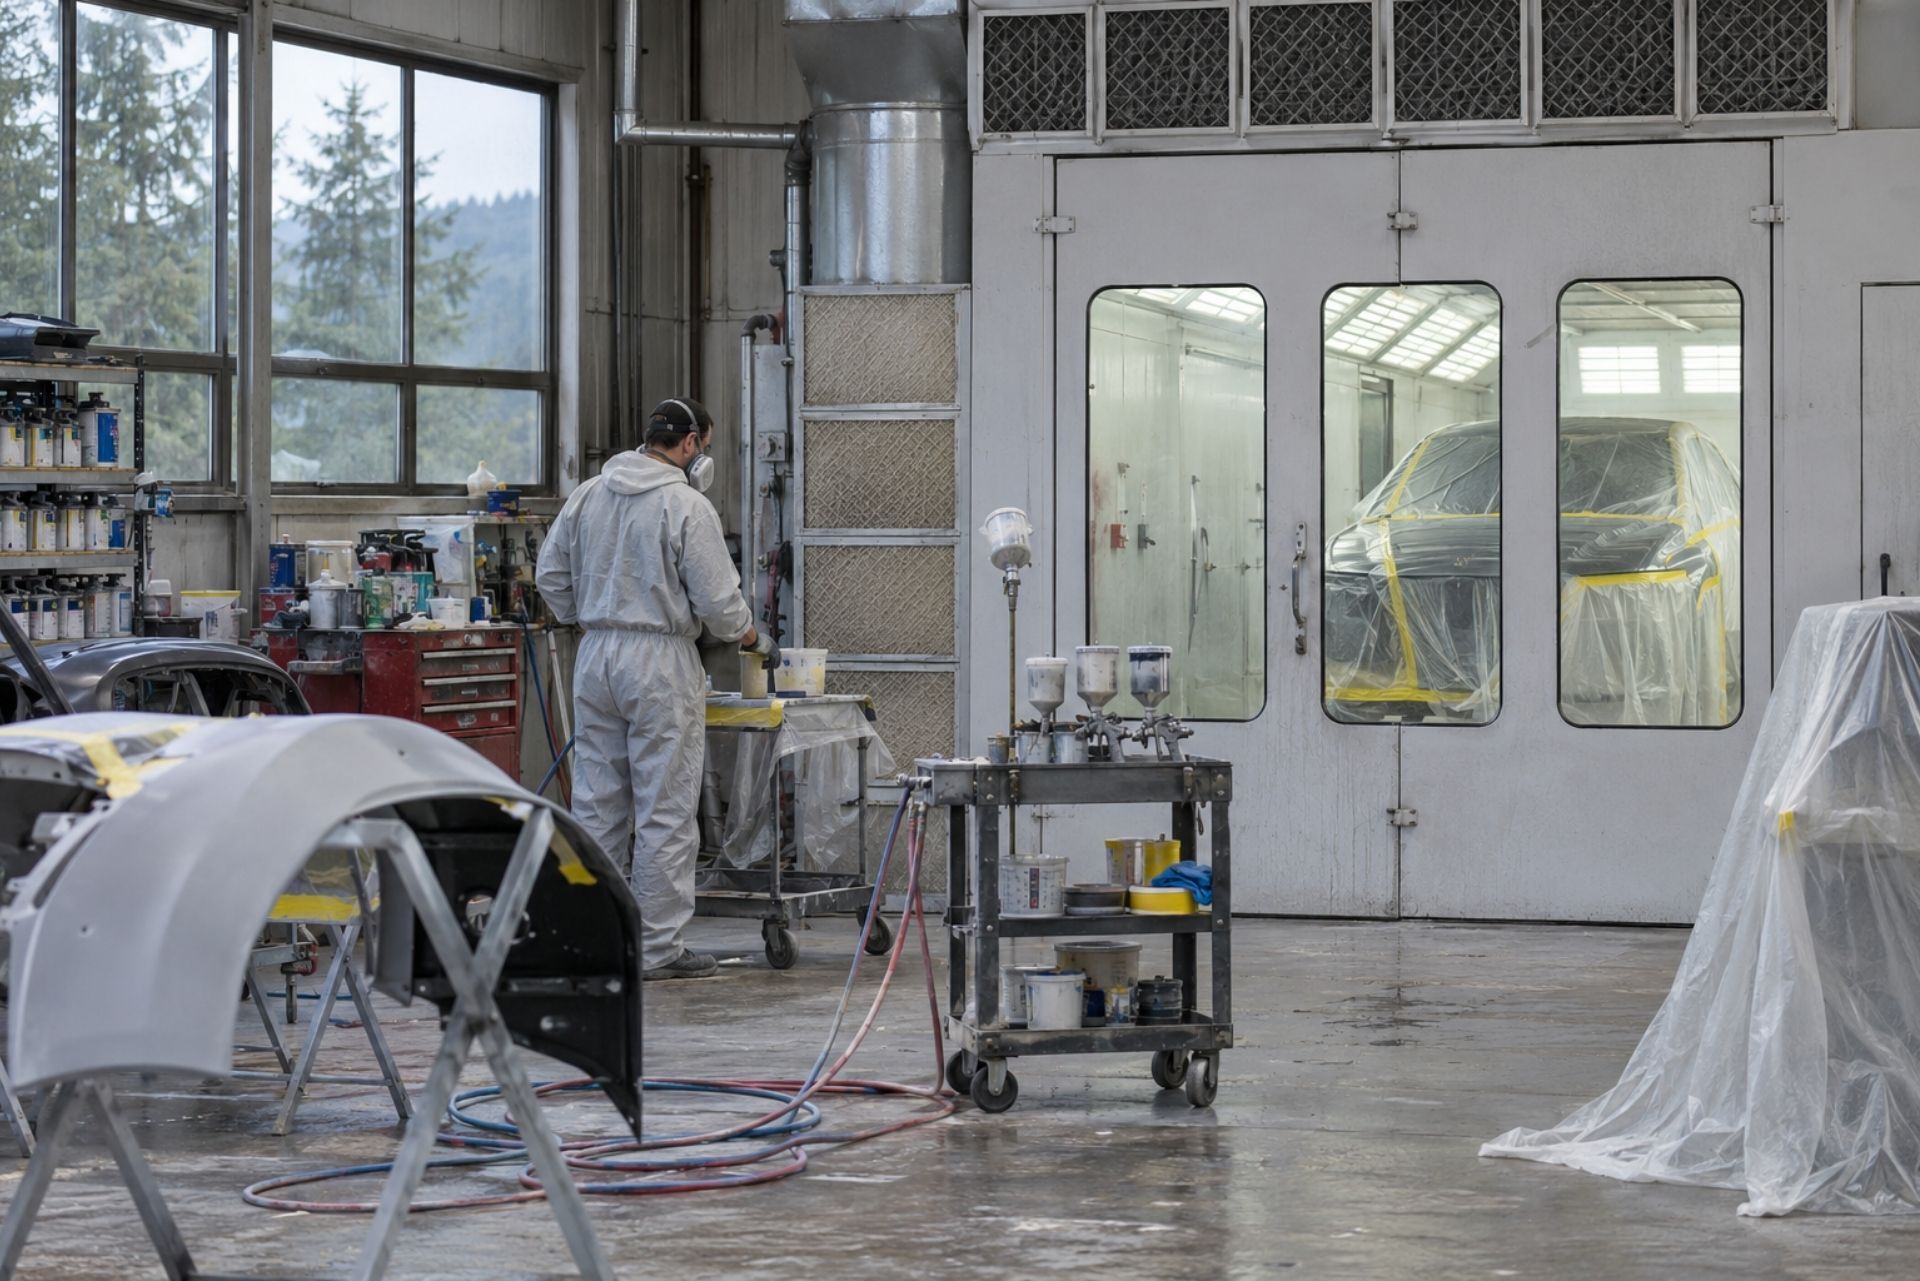
Most general liability policies carry a broad pollution exclusion. For a body shop, that leaves a real gap. Solvents, paint waste, used thinner, sanding dust, and overspray can all contaminate soil, storm drains, or neighboring property.
Washington takes this seriously. Refinishers must use high-efficiency application methods like HVLP spray guns to meet state VOC limits for automobile refinishing. Shops that generate dangerous waste also face reporting obligations and fees through the Department of Ecology's business waste program. Noncompliance can mean fines, but the bigger financial threat is cleanup liability.
Cleanup costs often dwarf penalties. If a solvent drum leaks into the soil behind your building, the remediation bill can climb into six figures. Washington's cleanup laws can also pull in the property owner, so landlords increasingly require tenants to carry pollution coverage.
Managing Overspray and Hazardous Waste Risks
Overspray claims usually start small. A neighbor's car parked downwind picks up a fine mist of clear coat. Then three more neighbors notice the same thing, and suddenly you're paying to correct paint on a whole row of vehicles.
Reduce the exposure with these steps:
- Inspect booth seals, doors, and exhaust filters on a set schedule, and log each inspection.
- Never spray outside the booth, even for quick touch-ups.
- Store solvents and waste in labeled, sealed containers with secondary containment.
- Use a licensed hauler for dangerous waste, and keep every manifest.
- Keep spill kits near mixing rooms and train every employee to use them.
When you shop for pollution coverage, ask whether it covers gradual releases or only sudden accidental events. Many contamination problems build slowly over years, and sudden-only coverage won't help with those.
Commercial Property and Business Interruption
Your building, or your tenant improvements if you lease, plus your inventory, office equipment, and supplies, belong under commercial property coverage. Body shops hold a lot of flammable material, so carriers look closely at construction type, sprinklers, and how you store paint.
Insure to replacement cost, not purchase price. Construction costs in the Puget Sound area have risen sharply, and a policy written on an outdated valuation can trigger a coinsurance penalty. If your limit falls below the required percentage of actual value, the carrier reduces your claim payment in proportion.
Washington adds regional risks. Western Washington shops deal with winter windstorms, heavy rain, and occasional snow loads. Eastern Washington operations face wildfire exposure, and smoke can contaminate drying finishes and shut down production even when flames never reach you. Confirm how your policy treats smoke damage and civil authority closures.
Business interruption coverage replaces lost income and pays continuing expenses like rent, loan payments, and key payroll while you rebuild. Most owners underestimate how long recovery takes. Replacing a custom paint booth can take months once you factor in permitting, manufacturing, and installation.
The catch is that many shops pick a 12-month indemnity period without checking booth lead times. Ask your booth vendor for a realistic replacement timeline, then set your restoration period with room to spare. Consider extended period of indemnity coverage too, since DRP relationships and customer volume don't return the day you reopen.
Washington Workers' Compensation Requirements
Washington is one of four states with a monopolistic workers' comp system. You can't buy workers' compensation from a private carrier here. Unless you qualify to self-insure, which few body shops do, you must get coverage through the Department of Labor & Industries.
This surprises owners who relocate from other states. If you hire employees, you need an L&I account, and you must report hours and pay premiums quarterly. Operating without coverage can expose you to penalties and to direct liability for injury claims, including the full cost of medical care and wage replacement.
Body shop work generates frequent and costly injuries. Common claims include:
- Back and shoulder strains from lifting panels and repositioning vehicles
- Burns from welding and plasma cutting
- Eye injuries from grinding debris
- Respiratory issues tied to isocyanate exposure in paint operations
- Lacerations from sheet metal and glass
That last group matters. Respiratory claims can develop slowly and run expensive, so a strong respirator fit-testing program protects both your crew and your claims history.
Understanding the State Fund (L&I) System
L&I charges premiums by the hour worked, not as a percentage of payroll like most states. Your rate depends on your risk class and your experience factor.
Auto body repair falls under Risk Class 3412. For 2027, L&I has proposed a 4.9% average increase across all classes, with Class 3412 facing a 2.0% increase to an hourly base rate of $1.6729. Your actual rate will shift up or down based on your experience modification, which reflects your own claim history.
Washington also lets employers deduct part of the premium from employee wages, which differs from most states. Your experience factor responds directly to claim costs, so returning injured workers to light duty quickly can keep your rates down. L&I offers wage subsidies through its Stay at Work program for exactly this purpose.
One gap to watch: L&I covers workplace injuries, but it doesn't provide stop-gap employers liability coverage. Add a stop-gap endorsement to your general or garage liability policy to cover lawsuits that arise from employee injuries outside the state fund's protection.
Comparison: General Liability vs. Garage Liability
Owners often ask whether they need general liability, garage liability, or both. The answer depends on how the policy is written, and the labels can mislead you.
Garage liability is built for automotive businesses. It combines premises and operations liability with auto exposures tied to your business, like moving customer cars and road testing. Standard general liability usually excludes auto-related claims entirely.
| Feature | General Liability | Garage Liability |
|---|---|---|
| Customer slip-and-fall | Covered | Covered |
| Faulty repair causing an accident | Often limited | Covered (completed operations) |
| Employee driving customer car | Excluded | Typically covered |
| Damage to customer vehicles in your care | Excluded | Excluded (needs garagekeepers) |
| Built for auto businesses | No | Yes |
Pay attention to that fourth row. Neither policy covers damage to customer vehicles in your custody. You still need garagekeepers on top.
Completed operations coverage deserves close attention. If a structural repair fails and the vehicle crashes months later, the injury claim can be enormous. Washington lawmakers have also considered rules on non-OEM parts and customer consent, so document parts choices and customer approvals carefully to defend repair-quality disputes.
Many carriers now package these coverages into a garage or auto service business policy. That can simplify things, but confirm every coverage piece is actually included rather than assuming the package covers everything.
Common Questions About Body Shop Insurance
Do I need garagekeepers if I already have garage liability? Yes. Garage liability excludes damage to customer vehicles in your care, so garagekeepers is the only policy that covers them.
Can I buy workers' comp from a private insurer in Washington? No. Washington requires most employers to buy coverage through L&I, the state fund, unless they qualify to self-insure.
What happens if a customer's car gets stolen from my lot overnight? With direct primary garagekeepers, your policy pays regardless of fault. With legal liability, it pays only if you were negligent, such as leaving keys in an unlocked car.
Does my property policy cover my paint booth breaking down? Usually not for mechanical or electrical failure. You'll need equipment breakdown coverage for that.
Is pollution coverage really necessary for a small shop? For most shops, yes. Even small solvent spills or overspray incidents can lead to cleanup and damage costs that general liability excludes.
How often should I review my coverage? Review at least annually and any time you add equipment, expand your lot, or take on DRP work that increases vehicle volume.
Before You Buy a Policy
A strong insurance program for a Washington collision shop matches how your business actually loses money. That means direct primary garagekeepers if you operate in a high-theft metro area, equipment breakdown for your booth and frame equipment, real pollution coverage, property values that reflect today's rebuild costs, and a clean L&I account with a stop-gap endorsement.
Before you request quotes, gather your exposures in one place:
- Your peak customer vehicle count and the highest total value on site
- A list of equipment with replacement costs and booth lead times
- Quarterly L&I hours and your current experience factor
- Three to five years of loss runs
- Your safety documentation: intake photos, booth logs, waste manifests
Then compare quotes from independent agents who write garage risks regularly. They can show you side-by-side differences in coverage forms, not just price. The shops that come through big losses intact rarely had the cheapest policy. They had the one that fit their operation.
About The Author:
Jackson Hering
I'm a fourth-generation insurance agent, having learned the business firsthand while working alongside my father. With years of experience passed down through my family, I take pride in combining that legacy knowledge with a modern, client-focused approach. I started my career at a small, family-owned agency and worked my way up, gaining a deep understanding of the industry from the ground up.
Contact Us
Coverage for Everyday Life
Personal Insurance That Works for You
We help individuals and families find coverage that keeps life moving—without overpaying or getting lost in fine print. From auto and home insurance to umbrella and life protection, our licensed team compares options across top-rated carriers to make sure you’re covered the right way, right now.
Auto Insurance
Drive with confidence and coverage that fits your needs.
Home Insurance
Coverage for fire, theft, liability, and more.
Renters Insurance
Affordable protection for your belongings and personal liability.
Boat Insurance
Coverage for watercraft damage, liability, and gear.
Life Insurance
Prepare for the future with term or whole life policies.
Umbrella Insurance
Extra liability protection for life’s bigger risks.
Protect Your Business Without the Guesswork
Business Insurance Built for Stability & Growth
Running a business comes with risk. We help reduce it. Our team builds custom coverage for your needs, including general liability, property, commercial auto, and cyber protection. We’re fast, responsive, and easy to reach—so your insurance is one less thing to worry about.
Industries We Serve
Tailored by Industry
We understand the risks unique to your business—and how to insure against them.
Contractors & Trades
We help contractors protect their tools, vehicles, job sites, and employees with comprehensive insurance solutions. Whether you’re a general contractor, electrician, plumber, or another trade, we provide the coverage you need to keep your projects moving forward safely.
Cannabis Industry
Mosaic specializes in insuring the unique risks of the cannabis industry, including growers, retailers, processors, and delivery services. We understand the compliance challenges you face and work with carriers who can protect every stage of your operation.
Lessor’s Risk (LRO)
If you own a building and lease space to commercial tenants, we help protect your property and liability as a landlord. Our policies safeguard your investment from damages, lawsuits, and other risks that come with leasing commercial real estate.
Frequently Asked Questions
Quick Answers. Trusted Support.
Insurance doesn’t have to be confusing. We’re here to make everything clear, helpful, and hassle-free.
What states is Mosaic Insurance licensed in?
Mosaic is licensed in more than 10 states, including Washington, Oregon, Arizona, California, Texas, Colorado, and more. Our team can help you whether you live locally in WA or operate across multiple state lines.
We’re especially well-equipped to help clients with multi-state businesses, real estate portfolios, or cannabis operations that need compliance-ready coverage in various jurisdictions.
Can I get quotes from multiple carriers through Mosaic?
Yes. As an independent agency, we partner with a wide range of top-rated insurance carriers. That means you’re not locked into just one company’s pricing or coverage limitations.
Our advisors compare quotes for you, break down the differences, and help you choose the plan that fits best—no pressure, just honest advice.
Does Mosaic offer cannabis insurance, and who qualifies?
Absolutely. Mosaic is one of the few agencies with deep experience in cannabis insurance. We offer coverage for dispensaries, cultivators, delivery services, manufacturers, and labs.
If you're in a licensed state and need coverage that meets regulatory requirements, we can help set you up with carriers who understand the cannabis industry’s unique risks.
What can I do through the client portal?
You can use our 24/7 client portal to request policy changes, submit certificates of insurance, and manage your billing. It’s easy to use and always available.
This helps speed up business tasks and gives you full access to your coverage—even outside of regular office hours.
What should I expect after requesting a quote?
Once you request a quote, our team will reach out to gather a few key details. From there, we shop coverage with multiple carriers and return with clear, personalized options.
We make it easy to compare policies, ask questions, and finalize your protection—usually in 24–48 hours.
Can Mosaic help me file a claim?
Yes. Whether it’s an auto accident, property damage, or business-related issue, we’re here to guide you through the claims process. Our team can explain your coverage, contact the carrier, and help get things moving quickly.
We’re your advocate—before, during, and after a claim. You don’t have to go it alone.
Tips, News & Insights
Explore Our Blog